

A home loan's EMI explained, and what prepaying saves.
A home loan's EMI, the interest over 20 years, the choices when the rate changes, and what a part payment saves, ending sooner or paying less.
By Suraj Kumar3 min read
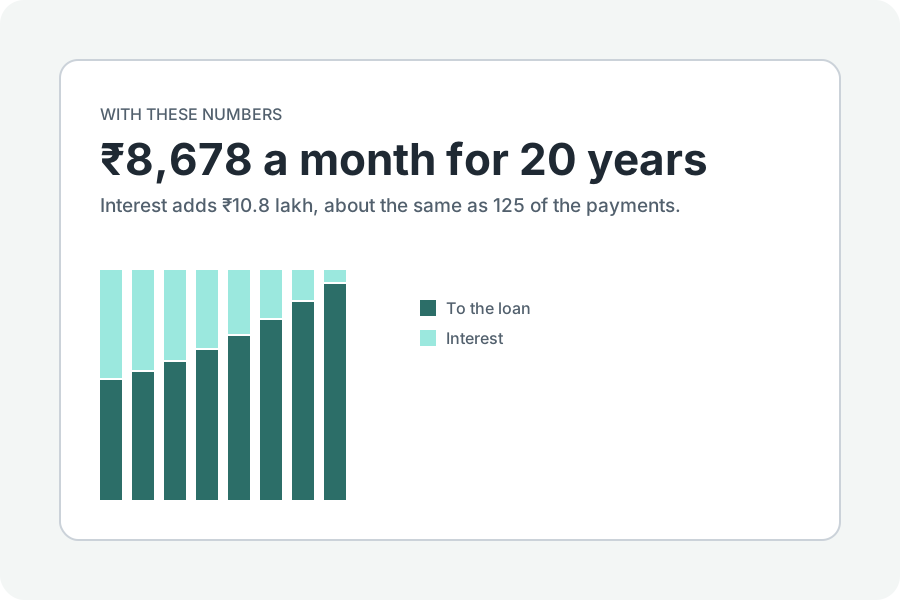
A home loan runs for decades, so small changes add up. Here is what moves the numbers most.
Interest over the years.
On ₹10 lakh at 8.5% for 20 years, interest adds about ₹10.8 lakh, more than the loan itself. Most of the early payments are interest.
When a floating rate changes.
RBI's rules ask lenders to let borrowers choose between a higher EMI and a longer term when a floating rate rises. The page shows both side by side, and says when keeping the EMI would no longer pay off the loan.
Paying part early.
₹1 lakh paid after the first year, keeping the EMI, ends the loan four years sooner; keeping the end date lowers the EMI to ₹7,792.79. Ending sooner saves about ₹2.19 lakh more interest.
Further reading
Topics: home loan emi calculator · home loan interest · housing loan emi · home loan prepayment · floating rate reset
A little less theory. A little more doing.
Try it on your own terms, with a free browser tool.
Try the tool